

This educational strategy is designed for traders who want a repeatable decision process. It defines location, confirmation and invalidation before entry; it does not claim a fixed win rate or return.
How the strategy works
The setup combines Ichimoku Cloud (Kumo), Tenkan-sen, Kijun-sen and market structure. Its advantage is selectivity: a signal counts only when price context and confirmation agree. The strategy is best treated as a checklist to test, journal and adapt to a specific broker—not as an automatic promise.
Use the stated 9/26/52 settings for the initial specification. Tenkan and Kijun are range midpoints; the cloud spans are plotted forward. The projected cloud is calculated from already known prices, not a forecast of future closes. Compare current price with the cloud aligned to that timestamp, not simply with the rightmost end of the drawing.
Indicators, markets and timeframe
Ichimoku Cloud (Kumo), Tenkan-sen, Kijun-sen and market structure.
Liquid major and JPY pairs with directional structure and stable spreads.
H1 and H4 for cloud structure; daily chart for broader directional context.
Timeframes are starting points, not guarantees. Lower timeframes produce more signals and more noise, spread impact and execution sensitivity. Confirm the higher-timeframe structure before taking a lower-timeframe trigger.
Entry rules
BUY checklist
- Price closes above the Kumo and the forward cloud is bullish or beginning to expand.
- Tenkan-sen is above Kijun-sen, confirming that short-term momentum supports the trend.
- A controlled pullback holds above Kijun-sen or the upper cloud boundary, followed by a bullish confirmation close.
SELL checklist
- Price closes below the Kumo and the forward cloud is bearish or expanding downward.
- Tenkan-sen is below Kijun-sen, confirming bearish momentum.
- A corrective rally fails below Kijun-sen or the lower cloud boundary and prints a bearish confirmation close.
Wait for the confirming candle to close. If the entry has moved so far that the planned stop no longer offers acceptable reward relative to risk, let the trade go.
The baseline is cloud breakout followed by a controlled pullback, not every Tenkan/Kijun cross. After the pullback confirmation closes, use the next executable quote if price still holds the required cloud/Kijun structure. A return into a repeatedly crossed cloud cancels the trend setup. A Kijun-based exit must specify whether a completed close or an intrabar level is used before testing.
Stop Loss and Take Profit
Stop Loss
Beyond the pullback swing and, when practical, beyond the relevant cloud boundary. If the full cloud makes the stop too wide, reduce position size or skip the setup.
Take Profit
Use the next structural high or low, a predefined 1.5R–2R objective, or trail behind Kijun-sen while price remains clearly separated from the cloud.
Calculate size only after defining the stop. Do not widen a stop after entry merely to avoid realizing a loss.
Risk management
Set a fixed account-risk ceiling per trade and reduce size when stop distance grows. Count correlated positions together. Predefine maximum daily and total drawdown, and stop trading when execution or market conditions differ materially from the tested plan.
Position size follows the stop: divide the planned cash-risk budget by the estimated loss per lot in the account currency at that stop, including costs. Round down to the broker’s volume step; if even the minimum lot exceeds the budget, skip. Here 1R is the initial entry-to-stop price distance; costs reduce the gross reward multiple.
Example trade walkthrough
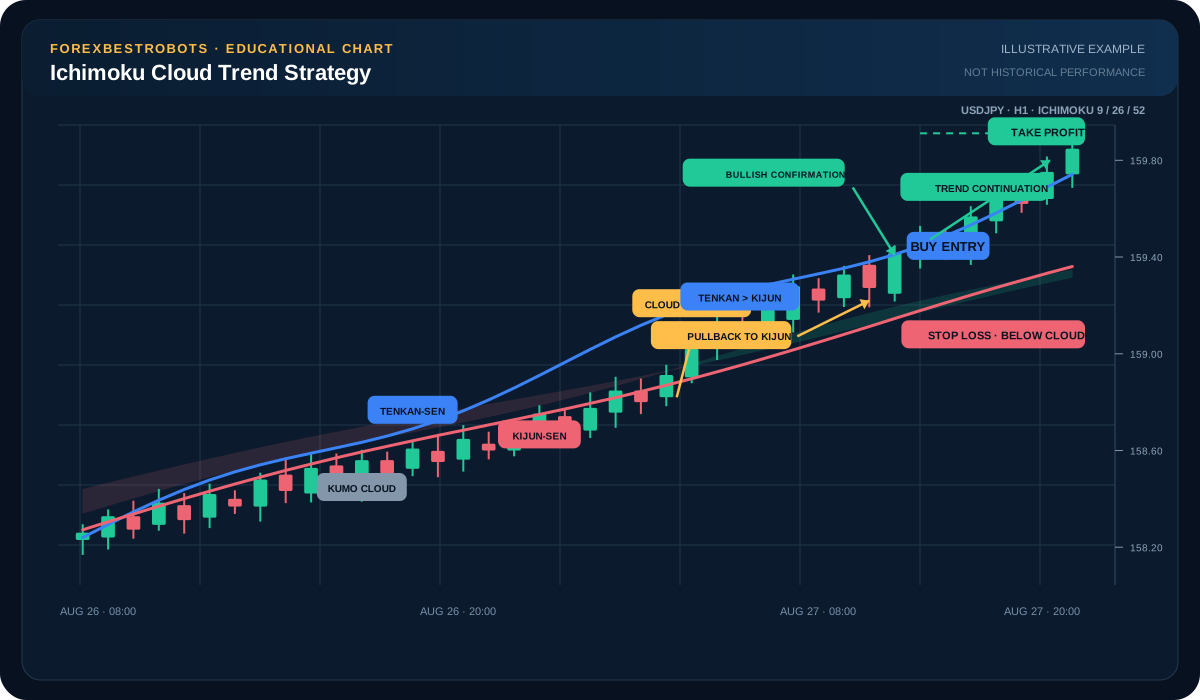
The USDJPY H1 schematic first places price above the cloud with Tenkan above Kijun. Price pulls back toward Kijun and closes bullishly while the structural low remains intact.
The next available quote is the candidate entry; the marked SL lies beyond the pullback and cloud boundary. The shown structural objective is a possible target, not a fixed return promise. If the full invalidation distance leaves insufficient reward or requires a lot below the broker minimum, the setup is skipped despite a valid cloud signal.
When to avoid this setup
A flat, very thin or repeatedly crossed cloud; Tenkan and Kijun moving sideways together; entries immediately into higher-timeframe resistance; and late entries after price is already extended far from Kijun-sen.
How to test it responsibly
- Write the rules in a checklist before looking at results.
- Mark historical examples without changing rules after each loss.
- Include spread, commission and missed fills.
- Separate development and out-of-sample periods.
- Forward-test on demo and record every valid signal, including skipped trades.
Align shifted cloud buffers correctly at every historical timestamp and allow enough warm-up history. Compare neighboring lookbacks and fixed-target versus predefined Kijun exits as separate runs. Record flat-cloud whipsaws, late signals and trading costs; no future candle may be used to classify a cloud break as valid.
No win rate, monthly return or “best strategy” claim is made. Results depend on market, costs, execution and rule discipline.
Technical reference: MetaQuotes.