

This educational strategy is designed for traders who want a repeatable decision process. It defines location, confirmation and invalidation before entry; it does not claim a fixed win rate or return.
How the strategy works
The setup combines Price range, optional ATR(14), session timing. Its advantage is selectivity: a signal counts only when price context and confirmation agree. The strategy is best treated as a checklist to test, journal and adapt to a specific broker—not as an automatic promise.
The retest version suits a defined consolidation followed by acceptance outside it. It is different from buying the breakout close or triggering a pending stop on a spike. A higher-timeframe barrier filter prevents a breakout from being bought directly into resistance; an entry-distance limit addresses late chasing.
Indicators, markets and timeframe
Price range, optional ATR(14), session timing.
Pairs consolidating before London or New York liquidity.
M15 to H1 for session ranges; H4 for larger structures.
Timeframes are starting points, not guarantees. Lower timeframes produce more signals and more noise, spread impact and execution sensitivity. Confirm the higher-timeframe structure before taking a lower-timeframe trigger.
Entry rules
BUY checklist
- Mark a range with at least two clear reactions at resistance and support.
- A candle closes above resistance with expansion; a wick alone is not a breakout.
- Enter on a successful retest of old resistance as support, or use a stop entry only with a tested momentum plan.
SELL checklist
- Define a well-tested range rather than a subjective single line.
- A candle closes below support with sufficient range expansion.
- Enter after old support rejects price as resistance or after your validated continuation trigger.
Wait for the confirming candle to close. If the entry has moved so far that the planned stop no longer offers acceptable reward relative to risk, let the trade go.
For the baseline, freeze the range before the break, wait for a completed close outside, then wait for a retest and rejection close at the broken boundary. Execute at the next available quote. Set the maximum retest wait before testing. A close back through the rejection swing or an expired wait cancels the candidate; no retest means no trade in this version.
Stop Loss and Take Profit
Stop Loss
Inside the old range beyond the retest swing. If that distance makes position size impractical, skip the trade rather than tightening blindly.
Take Profit
Use the measured range height, the next major level, or a risk multiple; reduce expectations if a nearby level blocks the projection.
Calculate size only after defining the stop. Do not widen a stop after entry merely to avoid realizing a loss.
Risk management
Set a fixed account-risk ceiling per trade and reduce size when stop distance grows. Count correlated positions together. Predefine maximum daily and total drawdown, and stop trading when execution or market conditions differ materially from the tested plan.
Position size follows the stop: divide the planned cash-risk budget by the estimated loss per lot in the account currency at that stop, including costs. Round down to the broker’s volume step; if even the minimum lot exceeds the budget, skip. Here 1R is the initial entry-to-stop price distance; costs reduce the gross reward multiple.
Example trade walkthrough
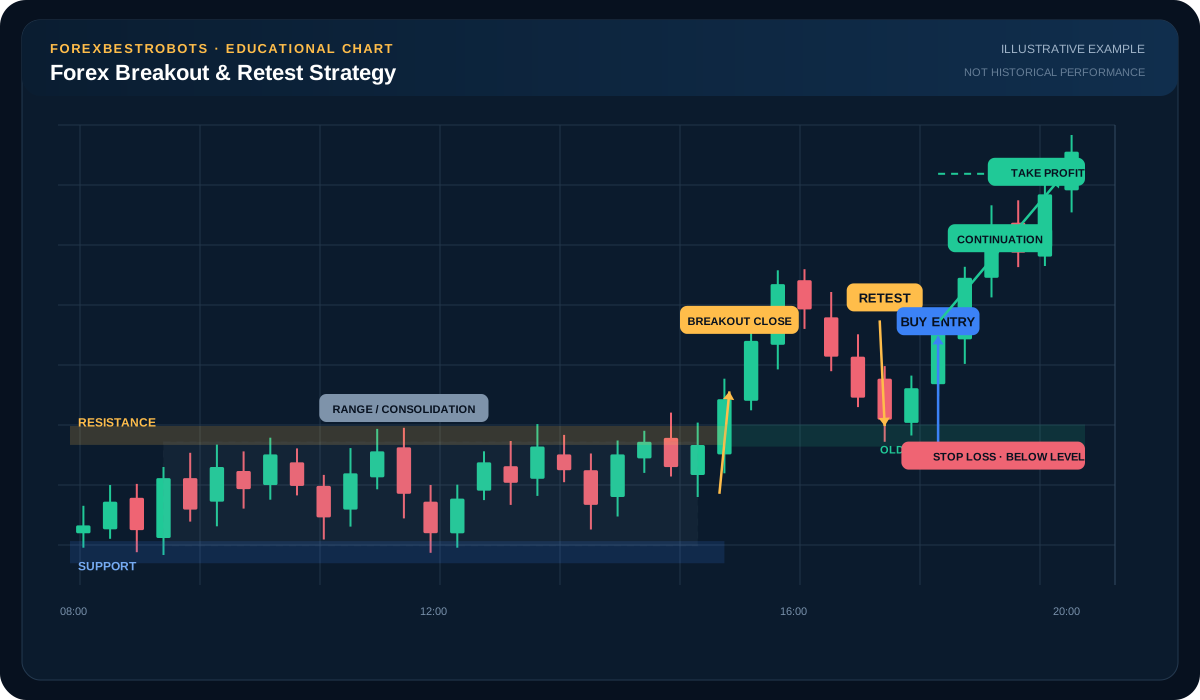
In the diagram, the first close above resistance only identifies a possible break. Price then returns to the former boundary and bounces from it as support. The BUY follows that confirmation; SL is inside the old range beyond the retest swing.
Choose the shown structural target only if its distance from the executable entry meets the preselected reward floor. The drawn continuation illustrates one possible path. A return through the retest swing instead triggers invalidation; a failed long is not automatically permission to open a short.
When to avoid this setup
Thin liquidity, spread expansion, a breakout directly into a higher-timeframe barrier, and chasing after price has already traveled most of the range projection.
How to test it responsibly
- Write the rules in a checklist before looking at results.
- Mark historical examples without changing rules after each loss.
- Include spread, commission and missed fills.
- Separate development and out-of-sample periods.
- Forward-test on demo and record every valid signal, including skipped trades.
Compare retest, close-entry and stop-entry as separate specifications, including missed retests and cancelled orders. Keep range definition and waiting limit fixed within each sample. Report eligible breaks as well as filled trades, costs and false-break clusters; a high fill rate alone says nothing about expectancy.
No win rate, monthly return or “best strategy” claim is made. Results depend on market, costs, execution and rule discipline.