

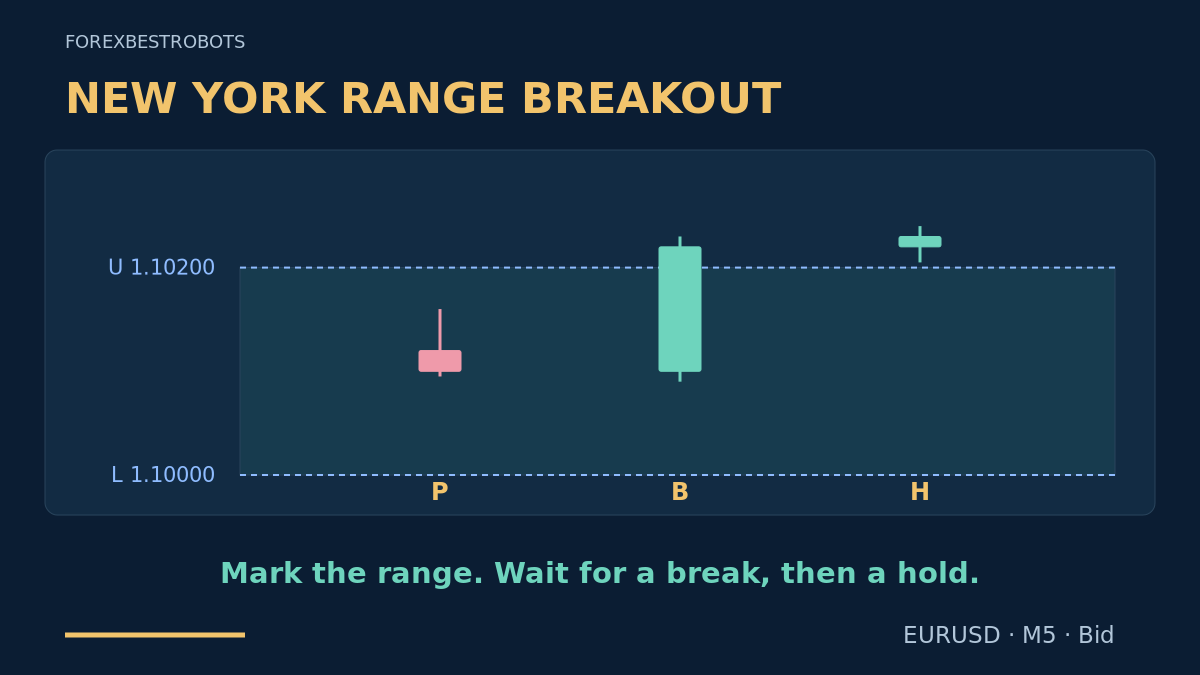
A breakout can close outside a box and immediately fall back inside. This model waits one more candle: the first closes beyond a frozen range, and the next must remain outside without touching the broken boundary. In plain language, mark the box, wait for the break, then check whether the next candle holds. That extra wait can also worsen the entry price, so confirmation never replaces a cost and risk check.
1. Give the third model a distinct purpose
The London opening-range strategy uses a range built after London's start and one later outside close. The Asian-range false-break model trades an immediate return inside. This model instead freezes a range before a New York decision window and requires two consecutive outside closes. It is a specific continuation test, separate from the broader New York session framework. A boundary retest is not confirmation here; keep that version separate.
2. Anchor the rules to New York's local clock
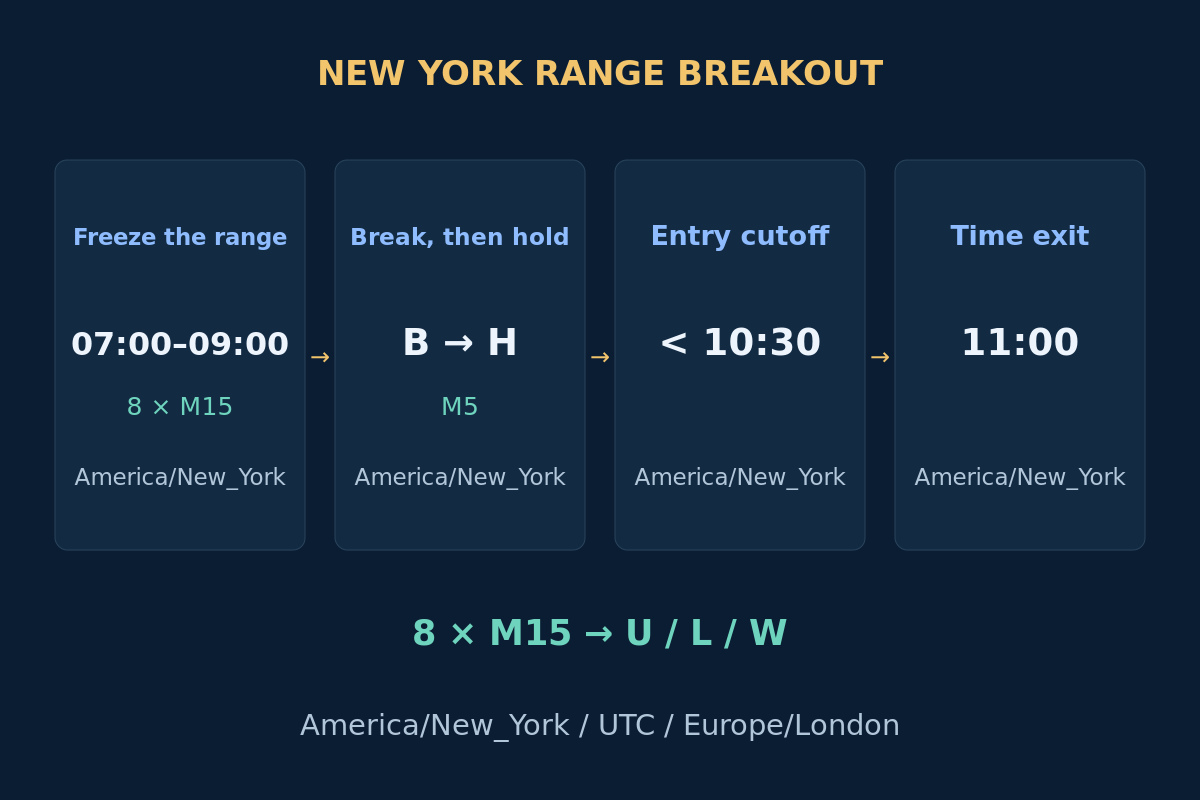
Build the reference during [07:00, 09:00) America/New_York on the trading date. This is a chosen research window, not a universal definition of the Forex or equity-market open. B may close from 09:05 through 10:20 inclusive; H must be the immediately following M5 candle, closing from 09:10 through 10:25. Submit strictly before 10:30; request closure of any remaining position at 11:00 New York.
Convert every historical date separately to UTC, Europe/London and broker time. On 2026-03-16, New York 09:00 is UTC 13:00 and London 13:00. On 2026-04-13, the same New York time is UTC 13:00 but London 14:00. The seasonal relationship changes because the US and UK move clocks on different dates. MT4 candle timestamps are opening times; the example labels closing times. See the session and time-zone guide.
3. Freeze the box and check whether the day qualifies
Use 8 valid, consecutive EURUSD M15 Bid candles opening from 07:00 through 08:45 New York. At 09:00 freeze U = max(High), L = min(Low) and W = U − L. Accept W from 20 to 60 pips inclusive; one pip is 0.00010 and the illustrative tick is 0.00001. Missing history, a closed market or an invalid width means no trade; do not redraw the box later.
At 09:00 require the just-completed M5 Bid close P in the central half: L + 0.25 × W ≤ P_close ≤ U − 0.25 × W. P must be valid and consistent with the final M15 close. Otherwise do not arm that day. This starting-location rule prevents beginning with price already at an edge; it does not establish balance or forecast expansion.
Before arming and again before entry, verify a current calendar with complete relevant EUR/USD event coverage. Skip the day if a selected high-impact event's exclusion [event − 15 minutes, event + 15 minutes) intersects [09:00, 11:00) New York. Fix provider, event families and impact definitions before testing. Missing or unverified coverage blocks entry. The news-risk guide explains overlaps and unscheduled surprises.
4. Consume the first outside close B once
The first M5 close strictly outside the box in B's permitted window consumes the day's single candidate across both directions, even if later rejected. For a possible BUY require 0 < B_close − U ≤ 0.20 × W and B_high ≤ U + 0.50 × W. For a possible SELL require 0 < L − B_close ≤ 0.20 × W and B_low ≥ L − 0.50 × W. In both cases require 0 < B_high − B_low ≤ W.
B's body may point either way; its completed outside close is the required fact. A wick alone or a close exactly on the boundary is not B. If the first outside close exceeds a limit, the day ends. Do not substitute a later breakout, change sides or reuse the range for another attempt after a loss or a failed confirmation.
5. Require the immediately next candle H to hold outside
BUY needs a bullish H with H_low > U, H_close ≥ B_close and H_high ≤ U + 0.25 × W. SELL needs a bearish H with H_high < L, H_close ≤ B_close and H_low ≥ L − 0.25 × W. These conditions demand a fully outside candle, no closing retreat toward the box, and limited extension. Equality is allowed in the close comparison and extension limit, but a boundary touch fails.
Only the immediately next M5 candle may confirm. A flat H, a missing interval, a later hold, a boundary touch or H closing after 10:25 ends the candidate and day. A later breakout retest belongs to a separate model. Waiting for H may filter some immediate returns while losing other opportunities; only comparable testing can establish the net effect.
6. Check one quote and place fixed protection
Inspect the first own-symbol quote received after H closes, within 15 seconds, with receipt age at most 2 seconds on verified clocks. Require tradable Bid < Ask, spread no greater than both 2 pips and 0.05 × W, and abs(Bid − H_close) ≤ 0.05 × W. Bid must remain strictly outside the broken boundary and no farther than 0.25 × W beyond it. Any observed post-H Bid return to that boundary, or touch of the projected Bid target before submission, cancels. Reject missing or inconsistent data; do not wait for a better quote. Submit before 10:30 New York.
BUY enters at Ask, with fixed Bid stop S = U − 0.25 × W and target T = U + W, both rounded down to valid ticks. SELL enters at Bid, with fixed Ask stop S = L + 0.25 × W + 0.00020 and target T = L − W + 0.00020, both rounded up. The projected Bid target for SELL is L − W. The short-side 2-pip conversion is an explicit allowance, not historical Ask data or a spread forecast. Check final price ordering and broker distances; do not tighten a stop to make the ratio pass.
Require no EURUSD position or pending EURUSD order anywhere in the account. Check permission, aggregate exposure, margin, volume and the cost test below. Establish valid stop and target protection with the initial order or do not open. After a confirmed fill, recheck these fixed levels, the unrounded cost ratio and the loss budget using the actual entry. A failed constraint or missing protection requests closure and records costs. A failed or uncertain order response consumes the day; reconcile broker state before further action.
7. Follow an invented BUY through confirmation
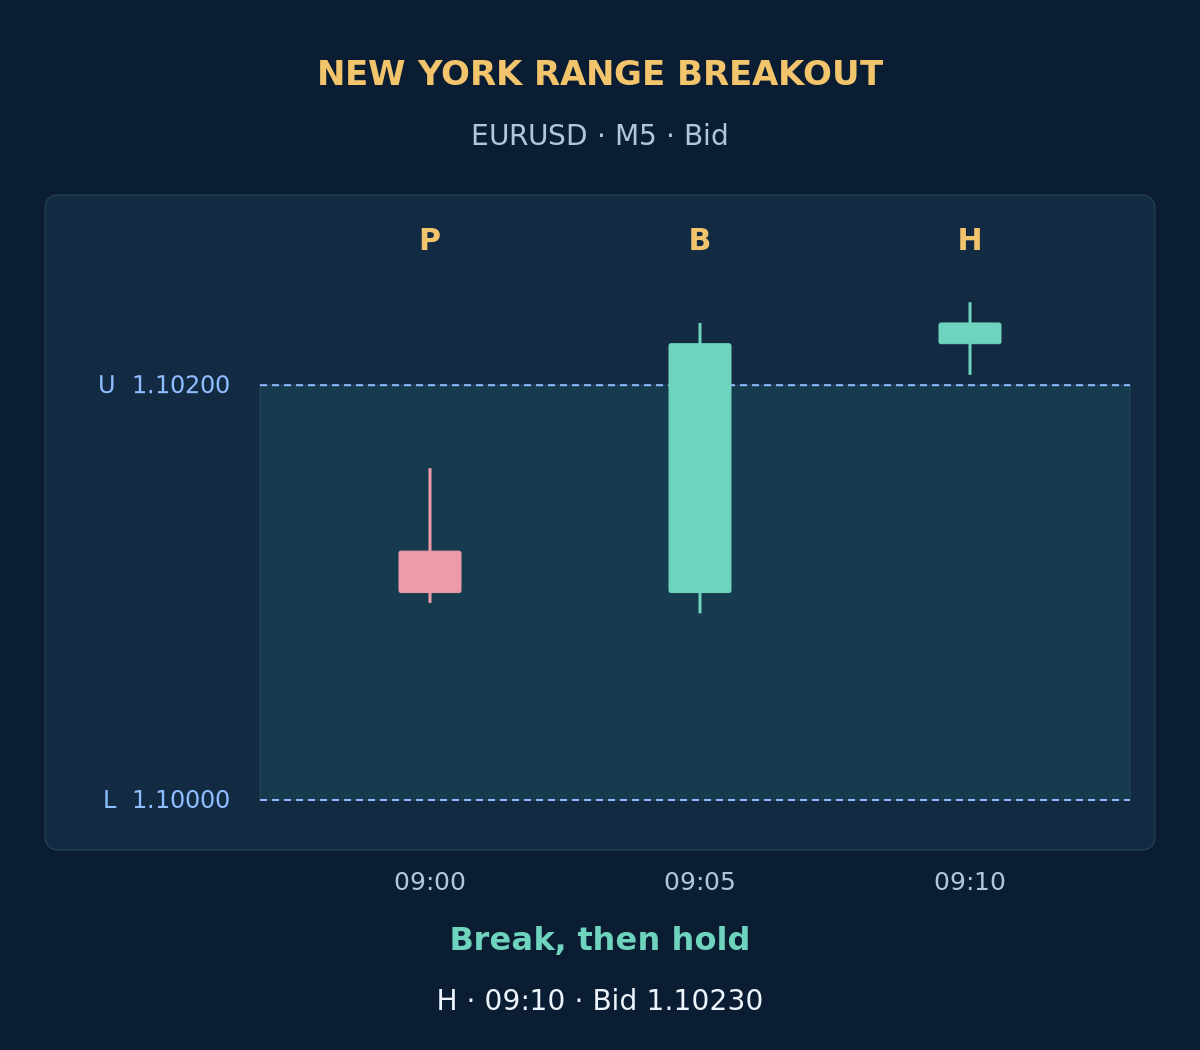
Assume a valid frozen U = 1.10200, L = 1.10000 and W = 20 pips. The table contains invented M5 Bid candles labeled by New York closing time on 2026-03-16. P closes in the central half. B closes 2 pips above U, inside the 4-pip close limit; its high is 3 pips above U, within the 10-pip extreme limit. Its 14-pip range is below W.
| New York close | Bid open | Bid high | Bid low | Bid close |
|---|---|---|---|---|
| 09:00 P | 1.10120 | 1.10160 | 1.10095 | 1.10100 |
| 09:05 B | 1.10100 | 1.10230 | 1.10090 | 1.10220 |
| 09:10 H | 1.10220 | 1.10240 | 1.10205 | 1.10230 |
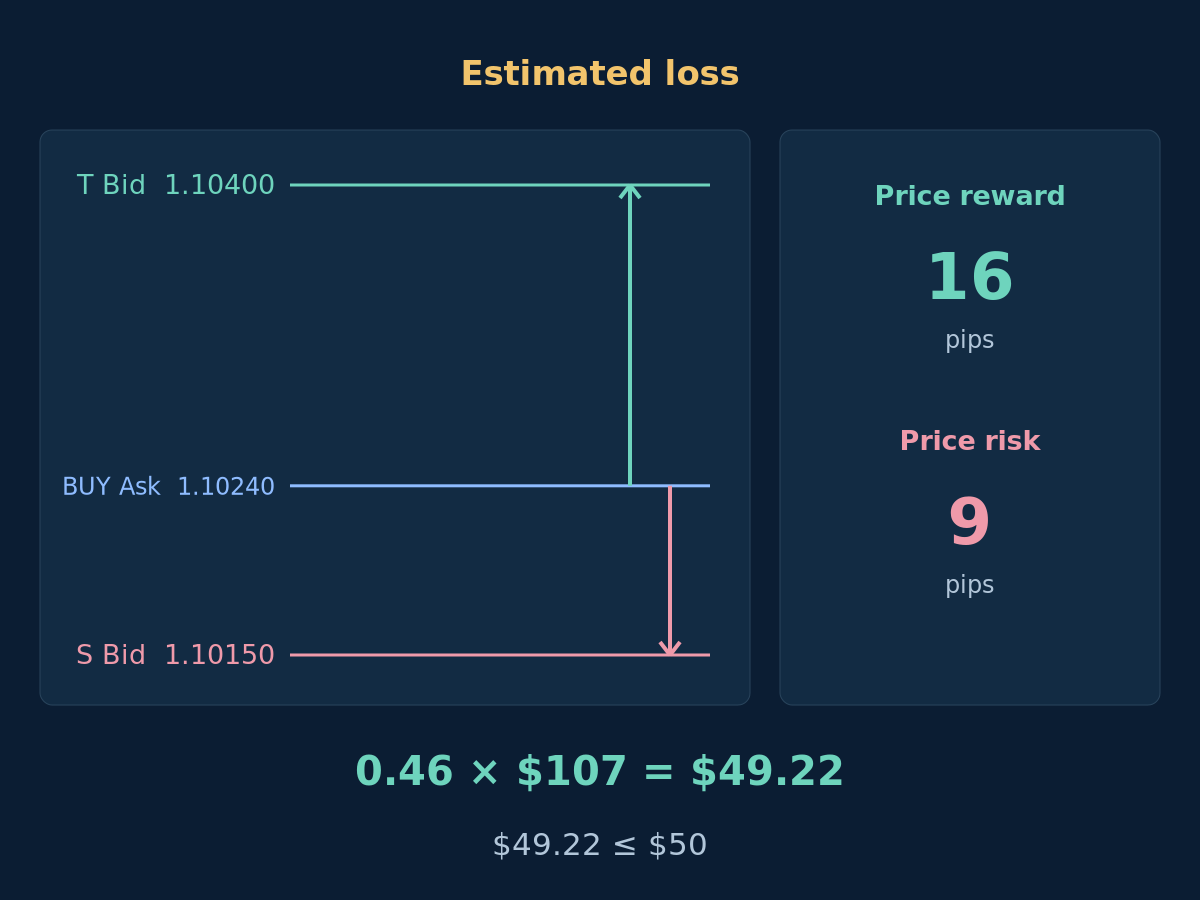
H is bullish, its low is strictly above U, its close is above B's close, and its high is 4 pips above U, within the 5-pip extension limit. Assume all calendar, data and order checks pass. The first quote at 09:10:01 is Bid 1.10230 / Ask 1.10240, with no intervening veto. A BUY fill at that Ask gives S = 1.10150 and T = 1.10400: 9 pips of risk and 16 pips of reward. No later exit is supplied.
If the first quote were instead Bid 1.10240 / Ask 1.10250, spread would still be 1 pip and Bid displacement 1 pip would meet the limit. Yet risk becomes 10 pips and reward 15 pips. With the costs below, Reward1 / Loss1 = $133 / $117 ≈ 1.14, below 1.25. Reject that quote rather than stretch the target or shrink the stop.
8. Let costs and the loss budget decide volume
Use illustrative equity $10,000 and a $50 loss budget, or 0.5%. At the accepted quote, estimated loss is $107 per lot. Volume 0.46 lots estimates $49.22 loss; the next step, 0.47 lots, estimates $50.29 and exceeds budget. The extra confirmation candle does not justify exceeding the budget. These are planning assumptions, not recommended risk or a guaranteed loss cap.
Show exact costs, lot size and the reference-candle recipe
Let dSL and dTP be positive executable entry-to-stop and entry-to-target distances in pips. Assume a USD account, 100,000 EUR per lot, pip value V = $10 per lot, total additional adverse execution s = 1 pip per outcome, round-turn commission c = $7 per lot and financing reserve f = $0. Fees scale linearly without a minimum. Use Loss1 = (dSL + s) × V + c + f and Reward1 = (dTP − s) × V − c − f. Spread inside the distances is counted once. Require positive estimates and Reward1 / Loss1 ≥ 1.25 using unrounded values. Example figures use decimal points; commas separate thousands.
Here Loss1 = (9 + 1) × $10 + $7 = $107 and Reward1 = (16 − 1) × $10 − $7 = $143, so $143 / $107 ≈ 1.34. With minimum and step 0.01 lot, floor(($50 / $107) / 0.01) × 0.01 = 0.46 lots. Then 0.46 × $107 = $49.22 and 0.46 × $143 = $65.78. These are alternative estimated outcomes, not two charges or realized results. Verify actual contract values, conversion, fees and margin; skip if the minimum lot is too large. See trading costs and account risk.
To reproduce the reference, repeat R1–R4 below twice in order, giving 8 consecutive M15 candles opening from 07:00 through 08:45 New York and ending at 09:00. Each close joins the next open. The final M15 close matches P; P's quoted M5 prices fit inside that final M15 candle. Reference OHLC does not specify every intervening M5 candle or tick. This is a reproducible price example, not historical execution evidence, and the cost ratio establishes no return, win rate or expectancy.
| Reference row | Bid open | Bid high | Bid low | Bid close |
|---|---|---|---|---|
| R1 | 1.10100 | 1.10160 | 1.10000 | 1.10070 |
| R2 | 1.10070 | 1.10200 | 1.10050 | 1.10160 |
| R3 | 1.10160 | 1.10180 | 1.10080 | 1.10130 |
| R4 | 1.10130 | 1.10170 | 1.10090 | 1.10100 |
9. Keep the exits fixed and stop on time
Keep accepted S and T unchanged: no trailing, break-even move, partial exit, averaging or automatic reversal. Earlier actual stop/target fills take priority. If still open at 11:00 New York, request closure at the first tradable quote, using Bid to close BUY or Ask to close SELL. An outage does not extend the deadline, though actual execution may be delayed. There is no second daily candidate after a loss, missed trade or uncertain response.
If required prices, clock mapping or calendar coverage becomes invalid while open, or a newly selected news exclusion intersects the remaining planned holding period, keep accepted protection and request closure when execution is available. Block new entries and reconcile orders after restarts. A plotted target or sent close request is not a fill. The EA session and news-filter guide explains the mechanics. Gaps, worse execution and changed fees can exceed the loss estimate.
10. Test whether the second close earns its delay
Replay the frozen M15 reference, P, first B, immediately next H, quotes, order responses and exits in timestamp order. Use real historical Bid/Ask ticks for side-specific triggers; the short conversion is not Ask history. If OHLC cannot resolve an intrabar stop/target sequence, use finer data or mark it unresolved under a declared conservative convention. MT4 modeled ticks are not automatically original records. See responsible EA backtesting.
Keep rejected candidates and no-trade days, including failed holds, news blocks, stale quotes, rejected orders and post-fill aborts. Compare one-close and two-close versions on the same dates, data and cost model as separate systems. Measure the cost of later entry, missed moves and time exits, not just the count of failed breaks. Reserve later chronological evaluation and forward demo checks. Stress width, hold conditions, costs and US/UK clock-mismatch periods without reporting only the winning variant; aggregate shared currency exposure.
- The date's New York, UTC, London and server mappings are verified.
- All 8 M15 reference candles and P are valid; fixed width and starting-location checks pass.
- The current calendar fully covers the required news policy.
- The first outside close B meets all excursion limits.
- The immediately next H holds entirely outside without excessive extension.
- The first quote, fixed protection and unrounded cost ratio pass.
- Volume, margin and combined exposure fit the budget; no EURUSD order or position blocks entry.
- The daily attempt, broker state and 11:00 exit will be tracked and reconciled.
11. Questions about two-close confirmation
Do two closes guarantee fewer false breakouts?
No. The rule rejects a particular immediate return but can still admit later failures. It may enter at a worse price or miss a move entirely. Compare complete net outcomes, including no-trade days, rather than assuming more confirmation is better.
May H touch the boundary and still count as a hold?
Not in this baseline. H must remain entirely outside, so a boundary touch fails even if H later closes outside. A touch-and-hold or retest version needs separate rules and testing.
Can London always be treated as five hours ahead?
No. The US and UK change clocks on different dates. Use the date-specific America/New_York and Europe/London conversions, then map to broker time. A fixed offset silently changes the tested window during mismatch periods.
Does a ratio above 1.25 establish positive expectancy?
No. It compares estimated planned loss and reward for one candidate. It does not measure outcome probabilities, time-exit frequency or the full distribution of costs and fills. Only a defined, validated result series can assess expectancy.
12. References and scope
NIST documents US clock conventions; MetaQuotes OrderSend documents entry quotes and order constraints. The session guide covers UK clock mapping. These references do not endorse the breakout rules or profitability. The range, two-close condition, time limits and cost threshold are authored research choices.
Forex and leveraged trading involve substantial risk. This material is educational, not investment advice. Past or simulated results do not guarantee future performance.